
More first-time buyers (FTBs) over 50
Recent data shows that there are more over 50s taking their first step on the property ladder.
According to analysis of Financial Conduct Authority (FCA) data, first-time buyers aged 51 or over increased significantly between 2020 and 2024, rising by 43% over this period. Those buying their first home at the age of 41 or over increased by 10.5% since 2020.
New ISA product for first-time buyers
In June, the government launched a consultation on the implementation of a new Individual Savings Account (ISA) product to support first-time buyers (FTBs).
The FTB ISA is due to be introduced in April 2028 and, once available, is intended to replace the Lifetime ISA (LISA). A key difference between the two products is that the new FTB ISA will have no upper age limit. Currently, you have to be under 40 to open a LISA, but the FTB ISA will be available to any new homeowner over the age of 18.
Plans to end ‘gazumping’ in England
A series of reforms have been announced which will improve the homebuying process in England and Wales, including putting a stop to ‘gazumping’.
In June, Starmer’s Labour Government unveiled plans to simplify and speed up housing sales. One key element is an end to gazumping - when buyers are outbid on a property after an offer has been accepted.
Navigating the homebuying process
Buying a home is an exciting prospect, but it can also come with stresses. From property hunting through to moving day, there is a lot to consider during the process.
The impact on wellbeing
According to research from Barratt Homes, 60% of UK homeowners said that the homebuying process took a toll on their mental wellbeing. An additional 35% experienced disrupted sleep, while 29% reported that their sense of financial security was impacted.

Changes in borrower behaviour
Analysis from Moneyfacts shows how borrowers’ priorities have shifted due to the economic impact of the Middle East conflict.
Mortgage rates have been fluctuating since March and the short-term economic outlook is still unpredictable. As such, borrowers are increasingly looking for more flexible mortgage deals in the hope that rates will come down soon.

Fewer buyers looking to renovate
Research from Yopa indicates that the majority of buyers are looking for homes that require little to no work.
According to the survey, 54% of people who bought a home in the last year were only prepared to make minor cosmetic changes to their new home. Meanwhile, 23% were looking for a fully modernised ‘turnkey’ property that was ready to live in.

Remortgage demand jumps
New analysis from Stonebridge suggests remortgage activity surged during the opening months of 2026 as borrowers reached the end of ultra-low fixed rate mortgage products arranged during the pandemic.
Sharp rise in applications
Stonebridge data shows that remortgage applications increased by 45.8% during Q1 2026. The rise comes as many homeowners are reaching the end of fixed rate products arranged when borrowing costs were significantly lower.

Pressure grows for Stamp Duty reform
Calls for Stamp Duty reform are continuing to grow as first-time buyers face rising purchase costs.
Research suggests first-time buyers have paid an extra £307m in Stamp Duty since the tax-free threshold changed in April 2025. On average, buyers have reportedly paid £4,618 more to complete a purchase over the past year.

Buyers delaying their next move
Many prospective buyers feel ready to move in 2026, but affordability concerns and uncertainty are still causing hesitation.
Confidence versus action
Research shows that 52% of prospective buyers believe they are ready to purchase a property this year. However, there remains a significant gap between confidence and actually making a move.
High property prices and the challenge of saving for a deposit continue to be major barriers for many households. Rising living costs and uncertainty around mortgage affordability have also made it harder for some buyers to feel financially prepared.
For first-time buyers in particular, balancing rental costs with saving for a deposit continues to be a significant challenge, despite improving confidence across parts of the housing market.
Some tips for property hunters
For many people, buying a home is one of the biggest financial commitments that they will make. But house hunting is not just about getting the price right; you also need to be confident that the property and location is right for you and your lifestyle. Here are some factors to consider when making your move.
House price update
House prices picked up in March, with annual growth rising to 2.2% according to Nationwide. This is an improvement on February, when prices rose annually by 1.0%. The average house now costs £277,186.
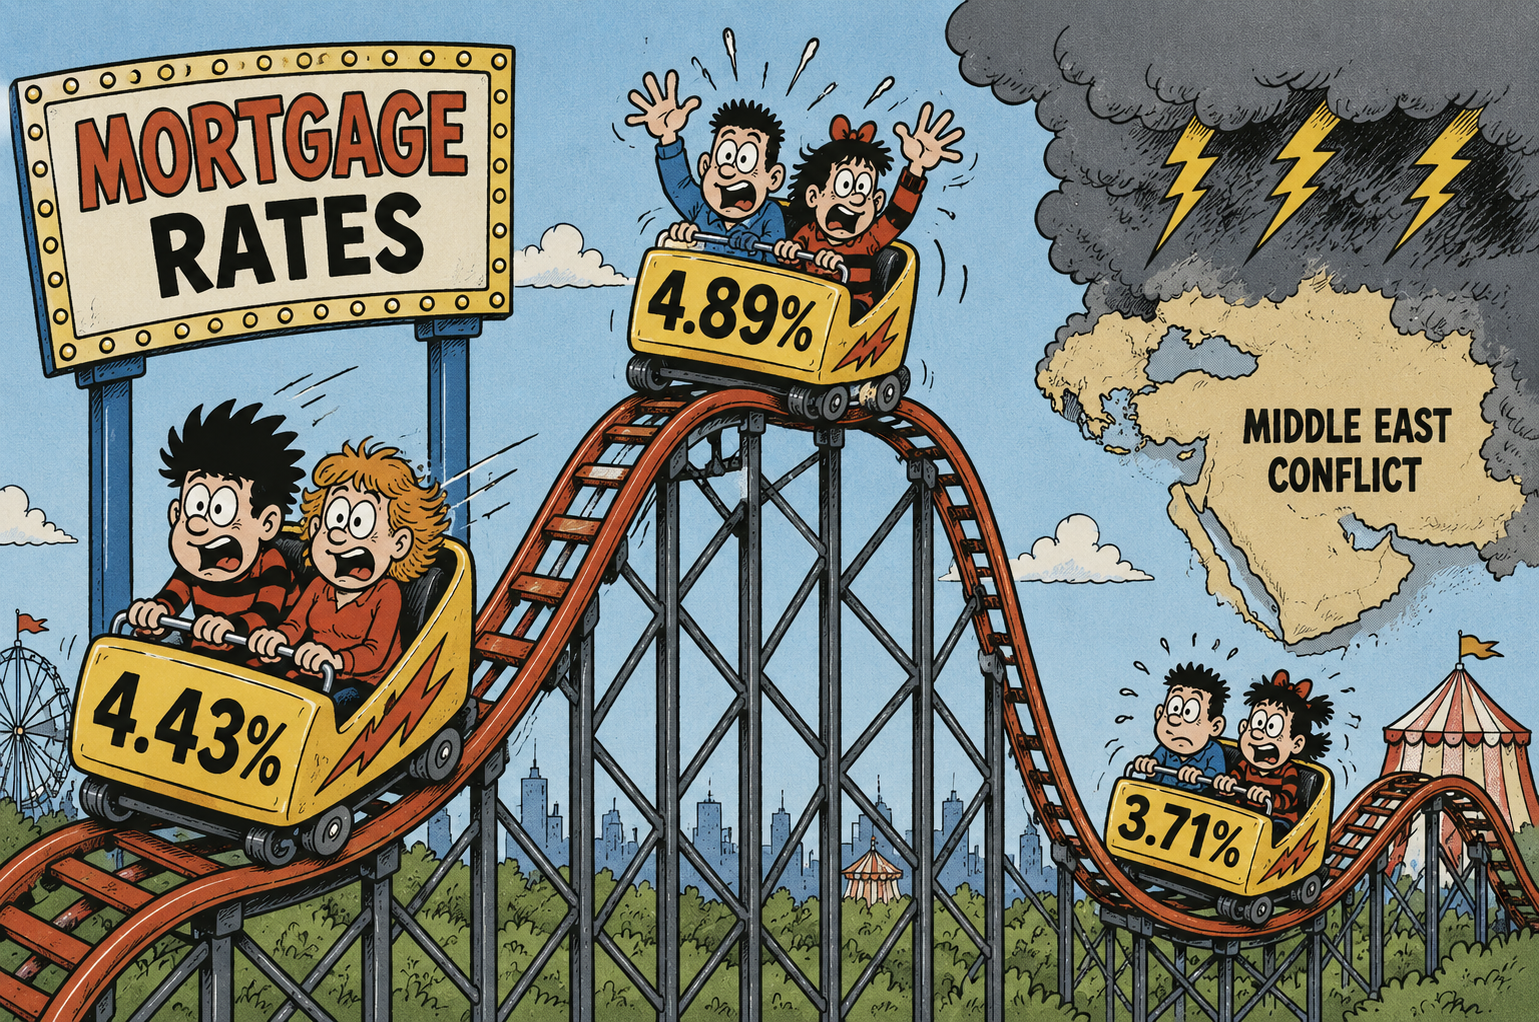
Fluctuating mortgage rates
Mortgage rates are in a state of flux in response to the Middle East conflict, which is a constantly evolving situation.
Mortgage rates were on the rise at the start of April, with over 30 lenders increasing their rates and withdrawing some products from the market. However, by the end of the month, lenders had started to make cuts again.
FTBs could be missing out
Many hopeful homeowners could be closer to getting on the property than they realise, but they are underinformed about their mortgage options.
A survey by the Building Societies Association (BSA) has found that nearly half (47%) of people who want to buy a home have never spoken to a lender or mortgage broker. This means that many prospective first-time buyers (FTBs) don’t fully understand what’s available, so could be missing out on an opportunity to become a homeowner.
Homes rising in value
Recent research has found that half of UK homes increased in value last year.
According to Zoopla, 15.2 million properties gained value by an average of £9,900 in 2025. Within this group, 3.1 million homes saw particularly strong growth, rising by more than £20,000. In contrast, 9.1 million households saw a decrease in value by an average of £10,800.
What’s happening to the mortgage market?
The mortgage market is facing uncertainty due to ongoing developments in the Middle East.
Affordability challenges had been easing slightly in recent months - mortgage rates were slowly coming down due to cuts to Bank Rate. In January 2026, the average monthly mortgage payment was 7% lower than the previous year.
The UK’s fastest-rising house prices
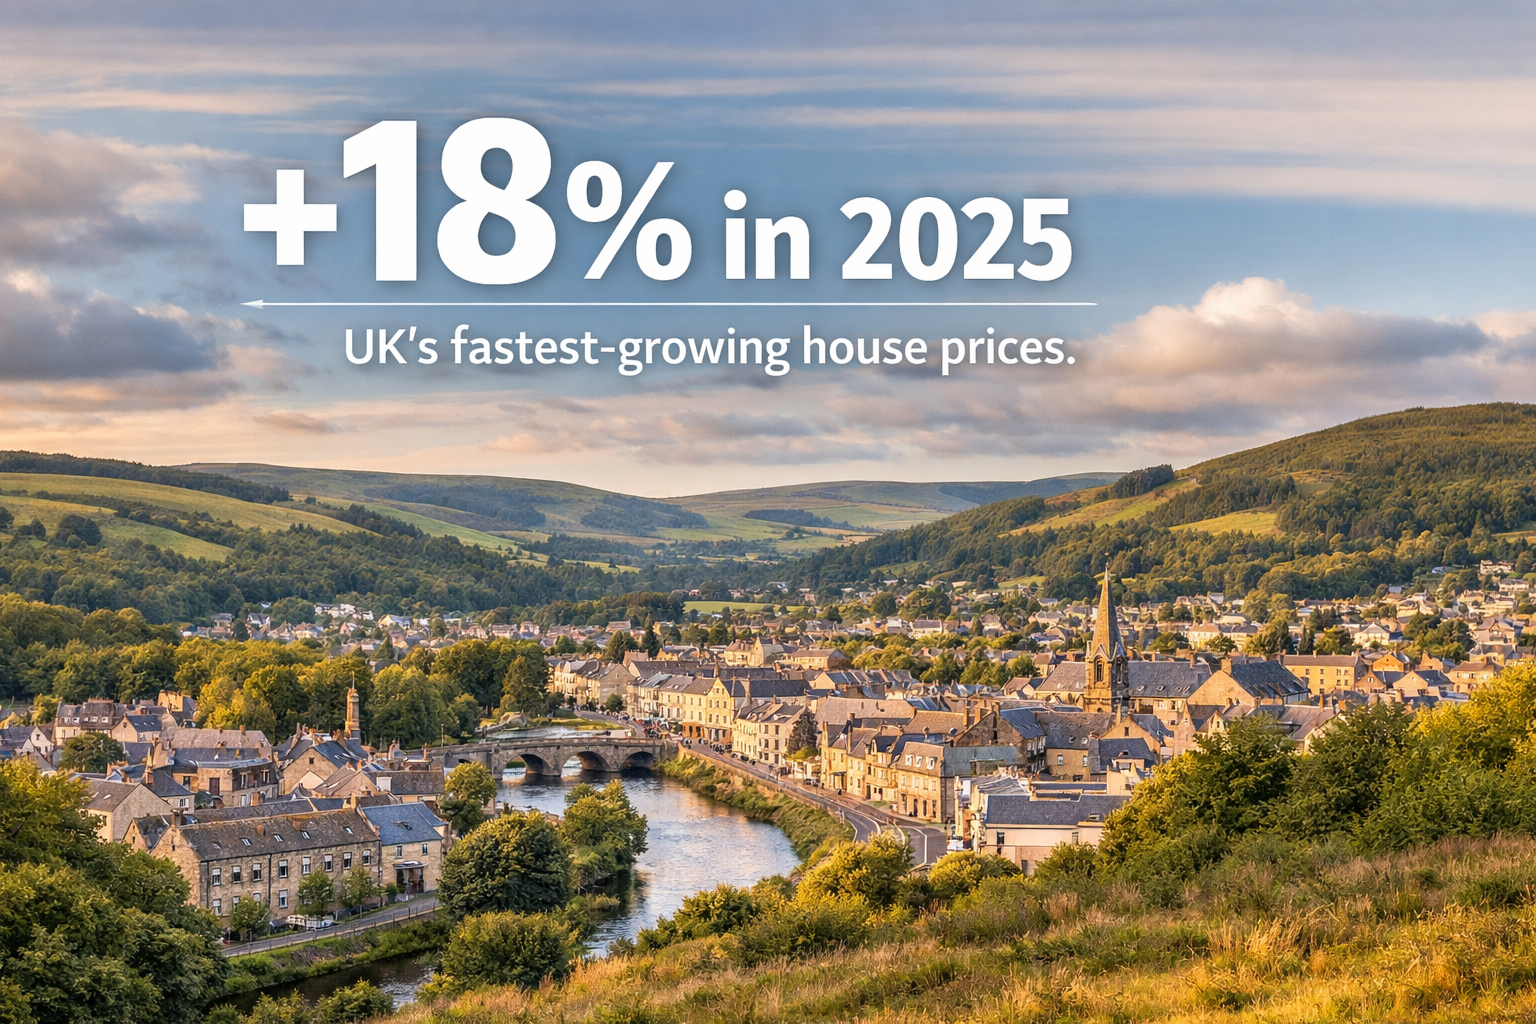
Research from Rightmove has identified the UK towns that recorded the strongest house price growth last year.
The list was largely dominated by towns in Scotland and the north of England. Hawick in the Scottish Borders saw the biggest annual rise, with prices increasing by 18% in 2025. Durham followed with a 15% increase, while Stannington in Sheffield saw prices grow by 12%.
A recap of 2025 housing reforms
Last year saw significant housing reforms for renters and homebuyers – here’s a recap of what you need to know.
Change to renters’ rights
The Renters’ Rights Act received Royal Assent in October 2025 and will come into force in three phrases this year. The initial phase of the rollout in May will include the much-awaited end to Section 21 ‘no fault’ evictions in England. Plus, all fixed term tenancies will automatically convert to periodic tenancies.
The rise of ultra-long mortgages
Data from the Financial Conduct Authority (FCA) indicates that more borrowers are opting for ultra-long mortgages in an effort to manage rising housing costs.
According to the analysis, in 2024 there were 116,276 mortgages taken out with repayment periods of 35 years or more. This is over three times the number sold in 2020, highlighting how borrowing conditions have changed significantly in recent years. As affordability challenges persist for buyers, longer mortgage terms help to reduce the cost of monthly repayments. While this can make finances easier to manage in the short term, it is more expensive in the long run.
2025 house sales show some promise
End of year statistics for 2025 offer some reasons to be optimistic about the housing market.
According to Zoopla, house sales for 2025 hit 1.2 million, the highest level for three years. First-time buyers showed growing confidence as they accounted for 39% of transactions last year.
Meanwhile, house prices lagged last year, with the average house valued at £270,300 at the end of 2025. This is up 1.1% on the previous year but is lower than the 10-year average of 3.8% growth. Zoopla expects prices to rise by 1.5% in 2026 while Rightmove’s outlook is more positive, at 2%.
Budget impact on landlords
Research suggests that landlords may be forced to raise rents to account for tax hikes announced in the Autumn Budget.
From April 2027, landlords will face a 2% tax increase on their rental income - the basic rate of property income tax will rise from 20% to 22%, while the higher rate will increase from 40% to 42%. Those paying the additional rate will pay 47%.